Veteran Home Buyers
Veterans, Homeownership, and the Value of Someone You Trust
By Detra Cox · November 5, 2026
A Veteran’s journey home begins with more than financing. Explore VA loan benefits, the possibility of using your benefit again, and the importance of choosing a REALTOR® you trust.
By Detra Cox | Detra & Company
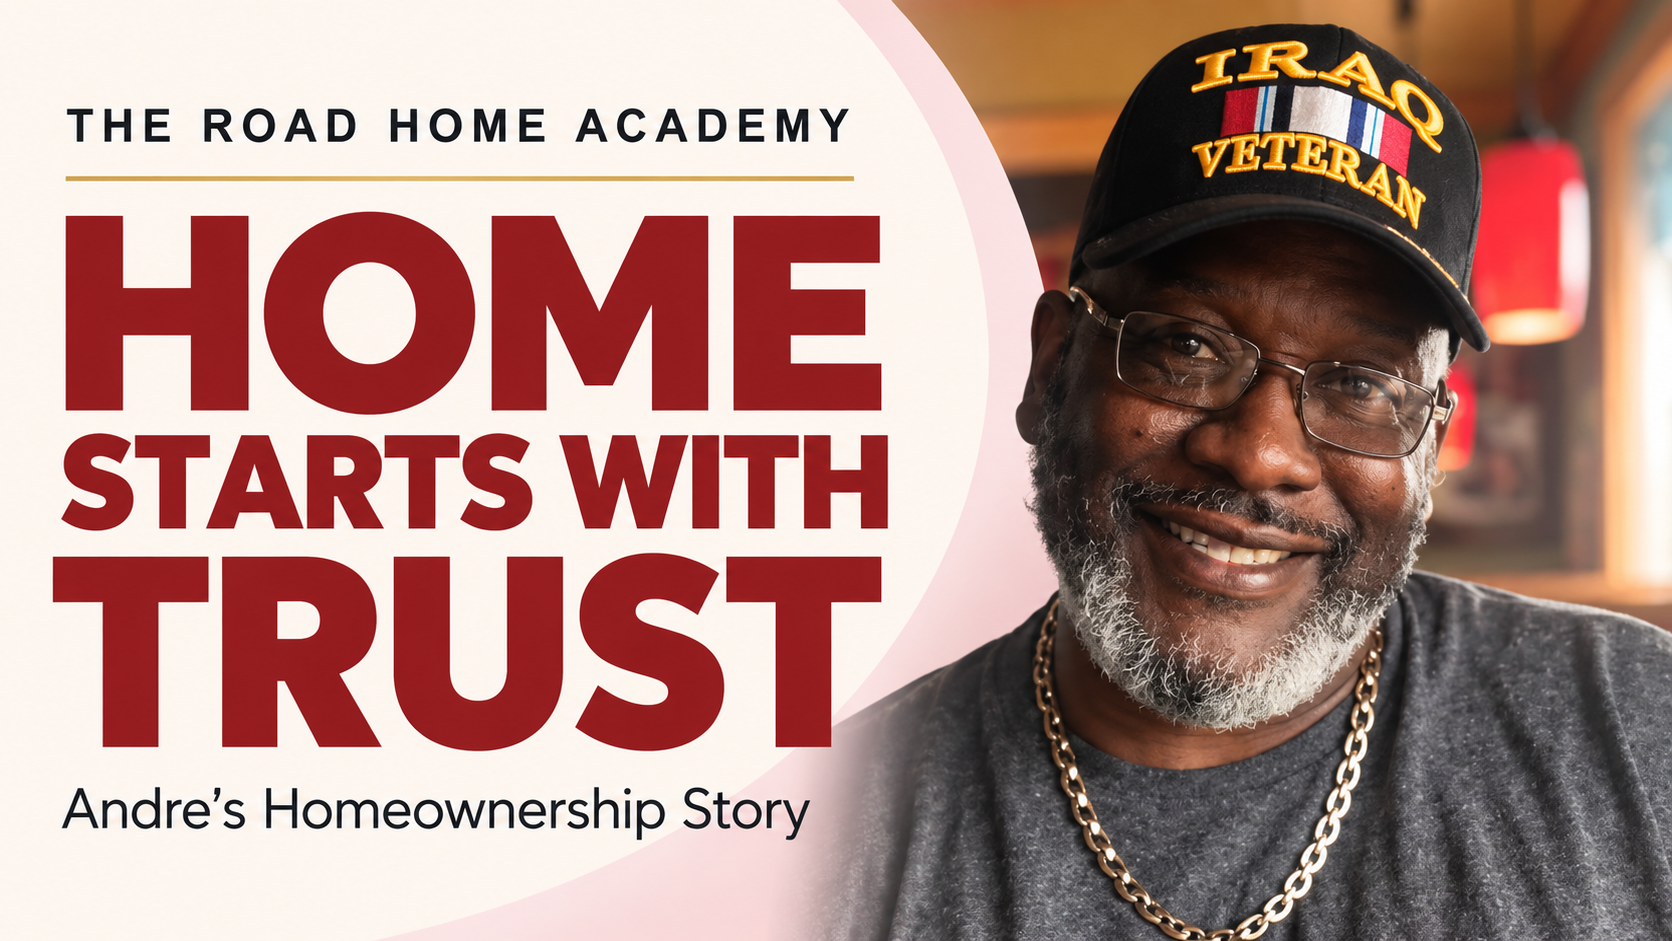
Before one of my classmates became my real estate client, he told me that when he bought a home, he wanted me to be his REALTOR®.
He wasn’t ready to buy yet. At the time, he was living in military barracks in Maryland and thinking about what his next chapter might look like.
Over the next couple of years, we stayed connected. We talked through the foundations - saving, managing credit, and preparing financially for homeownership. When the time was right, he purchased his home and officially made the move to North Carolina.
What stayed with me most was why he reached out.
He trusted me.
He wanted someone in his corner who would listen, explain the process clearly, and guide him to a home that truly fit his lifestyle and future goals.
Watch Andre share his journey to homeownership.
A relationship built before the home search
I’ve had the privilege of working with Veterans at different stages of life, including Veterans with service-connected disabilities. Each person brings different priorities, experiences, and questions.
A disability rating doesn’t tell me what someone needs in a home. A conversation does.
For one buyer, fewer stairs may matter. For another, the priorities may be proximity to medical care, space for visiting family, a manageable yard, or a comfortable monthly payment.
My responsibility begins with listening.
Military service is part of my family’s story, too. My father served in the Marine Corps, and my stepfather served in the Navy. I haven’t served myself, and I won’t pretend to know every Veteran’s experience. What I can offer is respect, patience, honest communication, and a commitment to follow through.
Understand the benefit you earned
For eligible borrowers, a VA-backed home loan can be a valuable path to homeownership.
Potential benefits include:
Purchasing with no down payment, when the transaction, available entitlement, appraisal, and lender requirements allow.
No monthly private mortgage insurance.
Competitive financing terms.
No prepayment penalty.
The opportunity to use the benefit again.
You don’t need a service-connected disability to qualify. Eligibility depends on applicable service requirements and other qualifying circumstances. A lender will also review your credit, income, and ability to repay.
No down payment also doesn’t automatically mean no money needed. Closing costs, inspections, moving expenses, and ongoing ownership costs still deserve a place in your plan.
Your VA benefit may serve more than one chapter
One misunderstanding worth clearing up is that a VA home loan is a one-time benefit.
Some Veterans can sell a home, pay off their VA loan, restore their entitlement, and use the benefit again. Others may have enough remaining entitlement to purchase another primary residence while keeping their existing home and VA loan.
But entitlement isn’t a personal spending account with unused dollars waiting to be withdrawn. It relates to the amount VA can guarantee for your lender.
With full entitlement, VA generally doesn’t impose a loan limit, although lender approval and the property’s value still matter. With remaining entitlement, county loan limits and entitlement already used can affect whether a down payment is needed.
A VA-experienced lender can review your Certificate of Eligibility and explain your particular options.
The new purchase must meet applicable occupancy requirements. This benefit isn’t a shortcut for buying a vacation home or a property intended solely as an investment.
Disability benefits may affect loan costs
Veterans receiving VA compensation for a service-connected disability are generally exempt from the VA funding fee. You don’t have to be rated 100% disabled for that exemption to apply.
Other exemptions also exist. Ask your lender to verify your status and explain the costs that remain.
What should trust look like in a REALTOR®?
Trust should show up in everyday actions.
Look for someone who:
Explains decisions without pressuring you.
Works comfortably with a lender experienced in VA financing.
Asks about your needs instead of making assumptions.
Clearly explains representation, compensation, and responsibilities.
Respects your privacy.
Follows through—and admits when a question belongs with your lender, attorney, or VA benefits specialist.
Sometimes the right next step is touring homes. Sometimes it is spending more time preparing.
You deserve someone who respects both.
Your next chapter starts with a conversation
Helping my classmate become a homeowner began long before we found his house. It began with a relationship, a goal, and the willingness to work toward it together.
Whether you’re buying your first home, returning to North Carolina, or exploring whether you can use your VA benefit again, I would be honored to help you understand your next step.
Detra Cox | Detra & CompanyUnited Realty Group336-270-9834 | detraandco.com
Guiding You on the Journey to Your There.
Loan eligibility, entitlement, exemptions, and approval depend on individual circumstances. Confirm your options with VA and a participating lender.
Your next step, together.
Have questions about buying, selling, or settling into your home? Let’s talk about what comes next.
Connect with Detra